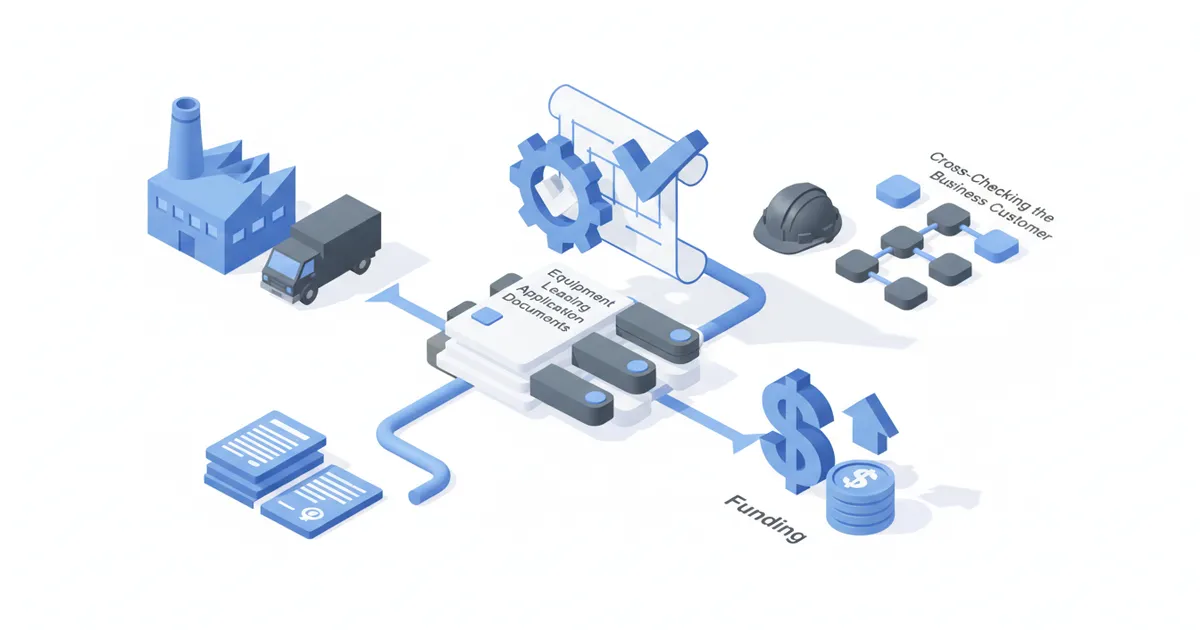
Equipment Leasing Application Documents: Cross-Checking the Business Customer Before Funding
Which field on which document to compare before an equipment lease funds: registry extract, accounts, signatory, bank details and supplier invoice. What a mismatch looks like and what to do next.

Summarize this article with
 ChatGPT
 Claude
 Perplexity
 Gemini
 Grok
Equipment leasing application documents only protect a lessor if they are compared with each other and with an official register before the supplier is paid. A complete file can still be wrong: the company name on the application differs from the registered name, the signatory is not a director, the bank account belongs to someone else. This guide lists the cross-checks, field by field, with what a mismatch looks like and the next step for the reviewer.
This article is for information only and is not legal or regulatory advice. Check current rules with your compliance function or adviser.
What a business lease file has to prove
A funding decision rests on four statements: the company exists and is who it says it is, the person signing can bind it, it can pay, and the asset exists and is what the lease schedule says. Each document supports one statement. The cross-check is the step that ties them together. For the wider document list, see our guide to equipment leasing compliance and the article on document errors that get leasing files rejected.
A typical UK application pack contains:
- application form and credit consent
- Companies House details (name, number, registered office, officers)
- latest filed accounts, plus management accounts for recent trading
- bank statements and a direct debit mandate
- ID and address proof for directors and any personal guarantors
- supplier quote or pro forma invoice
- insurance cover note for the asset
The cross-check matrix
| Field on document A | Compared with | Typical mismatch | Reviewer's next step |
|---|---|---|---|
| Legal name and company number on the application | Companies House record; name on contract and direct debit mandate | Trading name used instead of registered name; digit transposed in the number | Correct the contract to the registered name; do not issue documents until the number resolves to the right entity |
| Registered office on the application | Companies House registered office; delivery address on the supplier invoice | Registered office is an accountant's address, equipment ships to a different site | Record the delivery site separately; confirm the site occupier or landlord consent for fixed equipment |
| Name of the signatory | Officers list at Companies House; board minute or authority letter | Signer is an employee or a director who resigned | Ask for written authority from a current director, or re-sign |
| Directors and shareholders given on the form | ID documents; persons with significant control entries | Name, date of birth or ownership percentage differ | Ask the customer to explain; update the beneficial owner record |
| Turnover and net assets stated on the form | Latest filed accounts (period end, figures) | Accounts are 16 months old; form shows turnover 40% above filed figures | Request recent management accounts and bank statements covering the gap |
| Account holder on the bank statement | Legal name on the mandate and application | Account is in a director's personal name or a sister company | Hold funding until the account is in the contracting entity's name, or document the reason |
| Equipment, serial number and price on the lease schedule | Supplier invoice and quote | Model, price or VAT treatment differs; invoice has no serial number | Get a corrected invoice from the supplier before payment |
| Supplier name and bank details on the invoice | Supplier record held by the lessor; supplier's own Companies House entry | New bank details on an invoice from a known supplier | Call the supplier on a number you already hold before releasing funds |
| Insured party, asset, value and period | Lease schedule and customer name | Insured is the supplier; value below asset cost | Request an amended certificate naming the lessee and the asset |
Company identity: application against the register
Companies House holds the registered name, number, registered office and officers of every UK limited company and makes this information public (Companies House). Its Find and update company information service shows the officers (current and resigned) and any registered charges.
Three comparisons matter:
- Name and number on the application, contract and mandate must match the register character for character. A trading name is not a contracting party.
- The company status must be active. A dissolved or in-liquidation entity is a stop, not a note on the file.
- Charges listed on the register against what the customer declared. A customer that says it has no other finance, while the register shows security granted to a bank or asset finance provider, needs an explanation.
A register lookup shows that an entity exists and what it has filed. It does not show that the person on your video call is its director, and it does not make a PDF extract authentic. Pull the record yourself rather than relying on a PDF the customer sends.
Signatory and ownership
The signatory check compares the name on the signature block with the officers list. A director appointed last month will appear; one who resigned will show a resignation date. If the signer is not a director, ask for a board minute or a power of attorney, and read it for scope and date.
For ownership, compare the shareholders and controllers the customer lists with the persons with significant control recorded on the register and with ID documents in the file. Where the Money Laundering Regulations 2017 apply to the lessor, customer due diligence on a company includes identifying its beneficial owners (Regulation 28). Whether they apply depends on the lessor's activities and supervision, so confirm that with your compliance team. Separately, credit to sole traders and some small partnerships can fall under FCA consumer credit rules; check fca.org.uk before treating a file as purely commercial.
For a deeper view of ownership chains, read our piece on company file and beneficial owner cross-checks.
Financial capacity: stated figures against filed accounts
Filed accounts are a lagging indicator, so the check is about the gap. Compare the period end date, turnover, net assets and director loans in the accounts with the figures on the form. Then look at how old the accounts are. A company with a December year end that applies in November has accounts about ten months old at best.
Small companies may file abridged or filleted accounts with limited detail, so a missing profit and loss account is not a red flag in itself. It does mean you need other evidence: three to six months of bank statements, recent management accounts, VAT returns if the customer will share them.
What a mismatch looks like in practice:
- Form says turnover of 2.4 million pounds, accounts say 1.7 million, no explanation of growth.
- Bank statements show credits that do not fit the stated trade.
- Accounts show a large director's loan owed by the company, but the form lists none.
The next step is a conversation and a request for evidence, not an automatic decline.
Bank details and the direct debit mandate
The account holder name must match the contracting entity. Compare the name on the bank statement header, the direct debit mandate and the application. Sort code and account number should be identical on all three. A statement in a sister company's name suggests the customer pays from a group account; that can be acceptable, but it must be recorded and approved, not discovered after the first missed payment.
Check statement continuity too: opening balance equals the previous closing balance, dates run without gaps, and the page count is complete. Gaps are a reason to ask for the bank's original download.
The asset: lease schedule against supplier invoice
Payment diversion and invoice errors both surface at this step. Compare:
- description, model and serial number on the invoice with the schedule
- price excluding VAT, VAT amount and delivery charges
- supplier legal name and bank details with what you hold for that supplier
- delivery address with the site declared by the customer
If the supplier's bank details have changed, confirm by calling a number from your own records, not from the invoice. If the invoice shows a supplier that is not trading according to its register entry, stop.
Then check the insurance certificate: insured party is the lessee, asset described, sum insured at least the asset value, cover period starts on or before delivery, and the lessor is noted as interested party or loss payee where the agreement requires it.
Questions business owners ask
Business owners on finance forums and in small business communities often ask the same things, and a reviewer should be able to answer them without jargon.
Why did the lessor ask for a director's personal ID when the company is the customer? Because the lessor has to identify who controls the company and who is signing, and may take a personal guarantee. The ID is compared with the officers and ownership records.
How old can my accounts be? There is no single rule. Many lessors ask for the latest filed accounts and want recent bank statements or management accounts when the year end is more than about nine to twelve months back. That is lender policy, not law.
Why does the name on my bank account matter? Because the lessor collects payments by direct debit and needs to be sure the account belongs to the party that signed.
Running the cross-check consistently
Manual review works for a handful of files a week. At volume, the weak point is consistency: one reviewer compares the registered office, another does not. A validation tool can compare the same fields every time, flag date and name differences, and queue exceptions for a person. It compares fields and dates across documents and registers. It does not prove that a document is genuine, so keep your existing fraud controls in place.
See how this works for lessors on the financing and leasing page, check pricing, or read how we handle files on our security page. The wider sector context is in the industry verification guide.
FAQ
What documents are required for an equipment lease application?
For a limited company: application form, registered company details, latest filed accounts, recent bank statements, ID for directors and guarantors, the supplier quote or invoice and insurance for the asset. Each one is compared with another document or the register.
What is the most common mismatch in a lease file?
Name differences: a trading name on the application and the registered name on Companies House. It looks minor but means the contract may name the wrong party.
Does a Companies House check confirm the customer is genuine?
It confirms the entity exists, its status, officers and filings. It does not confirm that the person applying is authorised, or that supplied documents are authentic.
How do I verify a supplier's changed bank details?
Call the supplier on a number from your own records and confirm the new details before releasing funds. Do not use contact details printed on the invoice that changed.
When should a file be escalated rather than corrected?
When the entity is dissolved, the signatory has no authority, or the account holder cannot be tied to the contracting party. Typo-level differences can be corrected with a signed amendment.
Stay informed
Get our compliance insights and practical guides delivered to your inbox.