Virtual Office KYC: Cross-Checking the Company File
Virtual office KYC in Canada: which fields on the address agreement, corporate registry record, beneficial ownership information and IDs to compare under FINTRAC rules, and next steps.

Summarize this article with
 ChatGPT
 Claude
 Perplexity
 Gemini
 Grok
Virtual office KYC is the review of a corporate client whose address is a shared office or mail service: you compare the address agreement, the corporate registry record, the beneficial ownership information and the directors' ID field by field, and you decide whether the file holds together. A virtual address is lawful and common in Canada. It cannot show where the business operates, so the consistency of the other documents has to carry the file.
This article is for informational purposes only and is not legal advice. Regulatory references reflect the position at the date of publication and apply to Canada unless stated otherwise. Quebec readers should see the French-language version for provincial specifics.
What a virtual address changes in a corporate client review
A virtual address removes one signal: where the people behind the corporation actually are. The address becomes a mail drop that may serve many corporations, so treat it as neutral. The weight shifts to whether the other documents agree with each other and with the public registry.
Reviewers often ask whether a mail-drop address is an automatic decline. It is not. Files fail when the address comes with other gaps, such as a director abroad with no explanation, ownership information that conflicts with the shareholder register, or a corporation incorporated weeks ago with no operating history.
Synthesis: under the Proceeds of Crime (Money Laundering) and Terrorist Financing Act and its regulations, a reporting entity opening an account for a corporation must obtain beneficial ownership information, including the names and addresses of directors and of everyone who owns or controls 25 percent or more of the shares, and take reasonable measures to confirm its accuracy (FINTRAC guidance). The file has to resolve to named individuals, whatever the address.
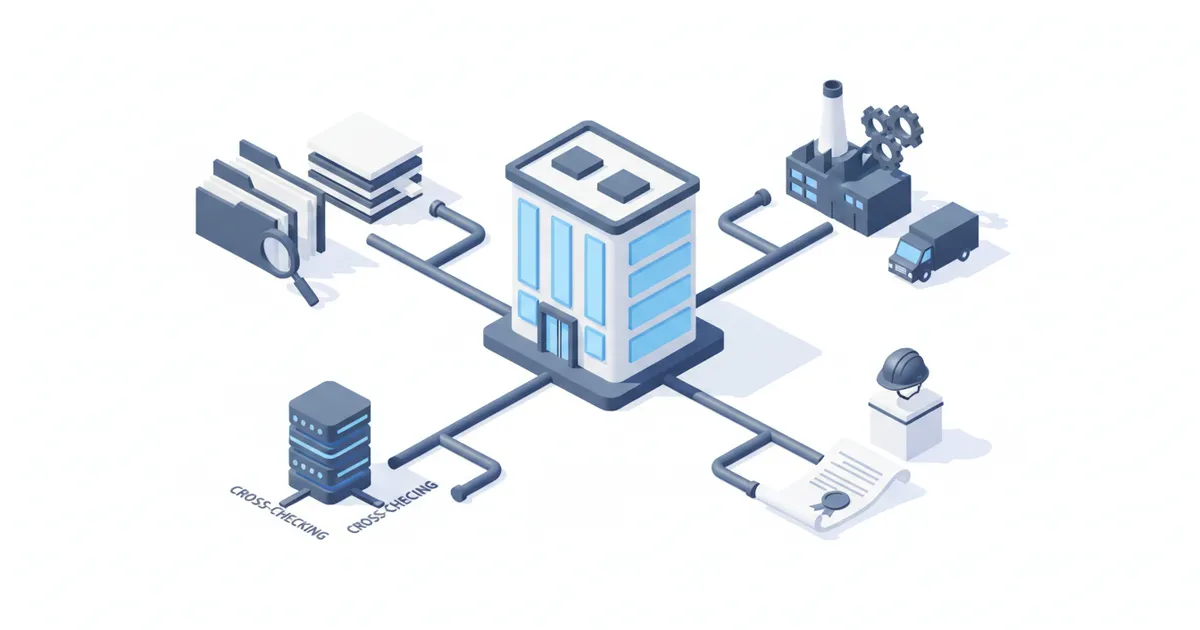
The cross-check map
Each row names the field on the first document, what it is compared with, how a mismatch looks, and the next step.
| # | Field on document A | Compared with | A mismatch looks like | Next step |
|---|---|---|---|---|
| 1 | Corporate name and corporation number on the address agreement | Certificate of incorporation and registry record (Corporations Canada or provincial registry) | Different legal form, dissolved status, name differing by one word | Request corrected agreement; do not onboard on the operating name |
| 2 | Address on the agreement | Registered office on the registry record | Agreement address differs, or an older address remains | Ask for the filed notice of change of registered office |
| 3 | Agreement start date | Incorporation date and change date | Agreement dated after incorporation without an earlier address | Ask where the corporation was located before |
| 4 | Directors and shareholders in the file | Registry record and shareholder register | Person in the file absent from the record, or the reverse | Request the current register of directors and securities register |
| 5 | Beneficial ownership declaration (names, percentages) | Securities register, articles and the individuals with significant control register | Declared 30% holder appears at 10%; holding company with no look-through | Request ownership chain to individuals |
| 6 | Director's ID (name, date of birth, expiry) | Director record and declaration | Birth date differs, name order differs, ID expired | Request valid ID; rule out transcription first |
| 7 | Director's proof of address | Address of the virtual office | Director's residence equals the mail drop | Request a residential proof |
| 8 | Account holder on the bank letter or void cheque | Legal corporate name | Account in an operating name or another entity | Request a letter in the legal name |
Cross-check 1: the address agreement against the registry
The agreement must name the same corporation, at the same address, as the registry. For federal corporations, the record sits with Corporations Canada; provincial corporations are held by their province's registry. Compare the corporation number first, since names are similar and numbers are not, then the address line by line, including suite or box numbers that providers use to distinguish clients.
A corporation's registered office must be in Canada, and for federal corporations in the province stated in the articles. A recent change of registered office shortly before an account request calls for a question about the earlier address.
Cross-check 2: the provider and what it proves
No single Canadian licence covers every virtual office operator, so do not assume supervision. Ask the provider for the signed agreement, whether it holds identification on the client, whether the address is shared, and how mail is handled, and keep the answers in the file.
This proves only that the provider has a relationship with the client. It does not prove the corporation operates from the address, and it is not a supervised AML check unless the provider tells you which regime applies. If the provider cannot be identified, treat the address as unverified.
Cross-check 3: ownership information against the securities register and the ISC register
Beneficial ownership information is the content most often wrong, mostly by accident. The question is whether the named individuals and percentages can be rebuilt from independent sources.
- Take percentages from the securities register or the articles.
- Apply the 25 percent threshold for shares or votes, plus control by other means.
- If a legal entity owns shares, follow the chain to an individual. Information that stops at a holding company is incomplete.
- For federal corporations, compare with the public register of individuals with significant control on Corporations Canada. Neither source is right by default; the difference is the finding.
FINTRAC also expects reporting entities to keep a record of the steps taken to confirm accuracy, and to record when they could not obtain or confirm the information. Our guide on beneficial ownership verification covers registries elsewhere, useful when a Canadian corporation is held by a foreign holding.
Synthesis: information supplied by the client is a starting point. The test is whether the reporting entity took reasonable measures to confirm it, and recorded what it did.
Cross-check 4: people against people
Directors' IDs are compared with the registry's director record, not with the address agreement. The fields that matter are full name, date of birth and expiry date. Name order and missing middle names are usually transcription errors; a different date of birth is not until shown otherwise.
Then compare the proof of address. If the director's residence is the mail drop, the document is not a residential proof. Founders often ask on business forums whether they can give their bank the virtual office address; the business address and the director's residence answer different questions, and the file needs both.
What to do when the file does not match
- Clerical gap: typo, name order, stale registry data. Request a corrected document and close the finding.
- Structural gap: percentages that do not add up, a missing holding, a director absent from the record. Pause and request the ownership chain.
- Unverifiable provider or address: apply enhanced measures, escalate to the compliance officer and consider whether a suspicious transaction report is warranted; our enhanced due diligence guide sets out the steps.
Record the comparison, not only the conclusion: which fields, which version of which document, on what date. A registry printout without a date is not defensible.
Where automation helps
Most of the eight rows are mechanical comparisons of names, numbers, dates and percentages. CheckFile's KYC and banking onboarding checks compare these fields across uploaded documents and flag differences for a reviewer. They check consistency and completeness, not authenticity, and the onboarding decision stays with your team. Data handling is on the security page and plans on the pricing page. Privacy obligations for the documents you collect fall under PIPEDA or provincial law.
For sector context, see the industry verification guide and the KYB document verification guide.
Frequently Asked Questions
Is a virtual office address a red flag for KYC in Canada?
No. It is lawful and common. It removes the address as evidence of where the business operates, so reviewers rely more on registry records, ownership information and the directors' documents.
Is the ISC register enough to identify beneficial owners?
No. It is a useful comparison point for federal corporations, but the client supplies the information, and a reporting entity must still take reasonable measures to confirm it with independent documents.
What should I ask a virtual office provider?
Ask for the signed agreement, whether the provider identified the client, whether the address is shared, and how mail is handled.
What if the ownership information does not match the registry?
First decide whether it is a clerical error or a structural difference. Do not onboard until you can explain the gap and have recorded the measures you took.
Does a perfect registry match prove the owners are correct?
No. It shows the documents agree with the registry, which relies on the corporation's own filings. Independent evidence such as the securities register is still needed.
Stay informed
Get our compliance insights and practical guides delivered to your inbox.